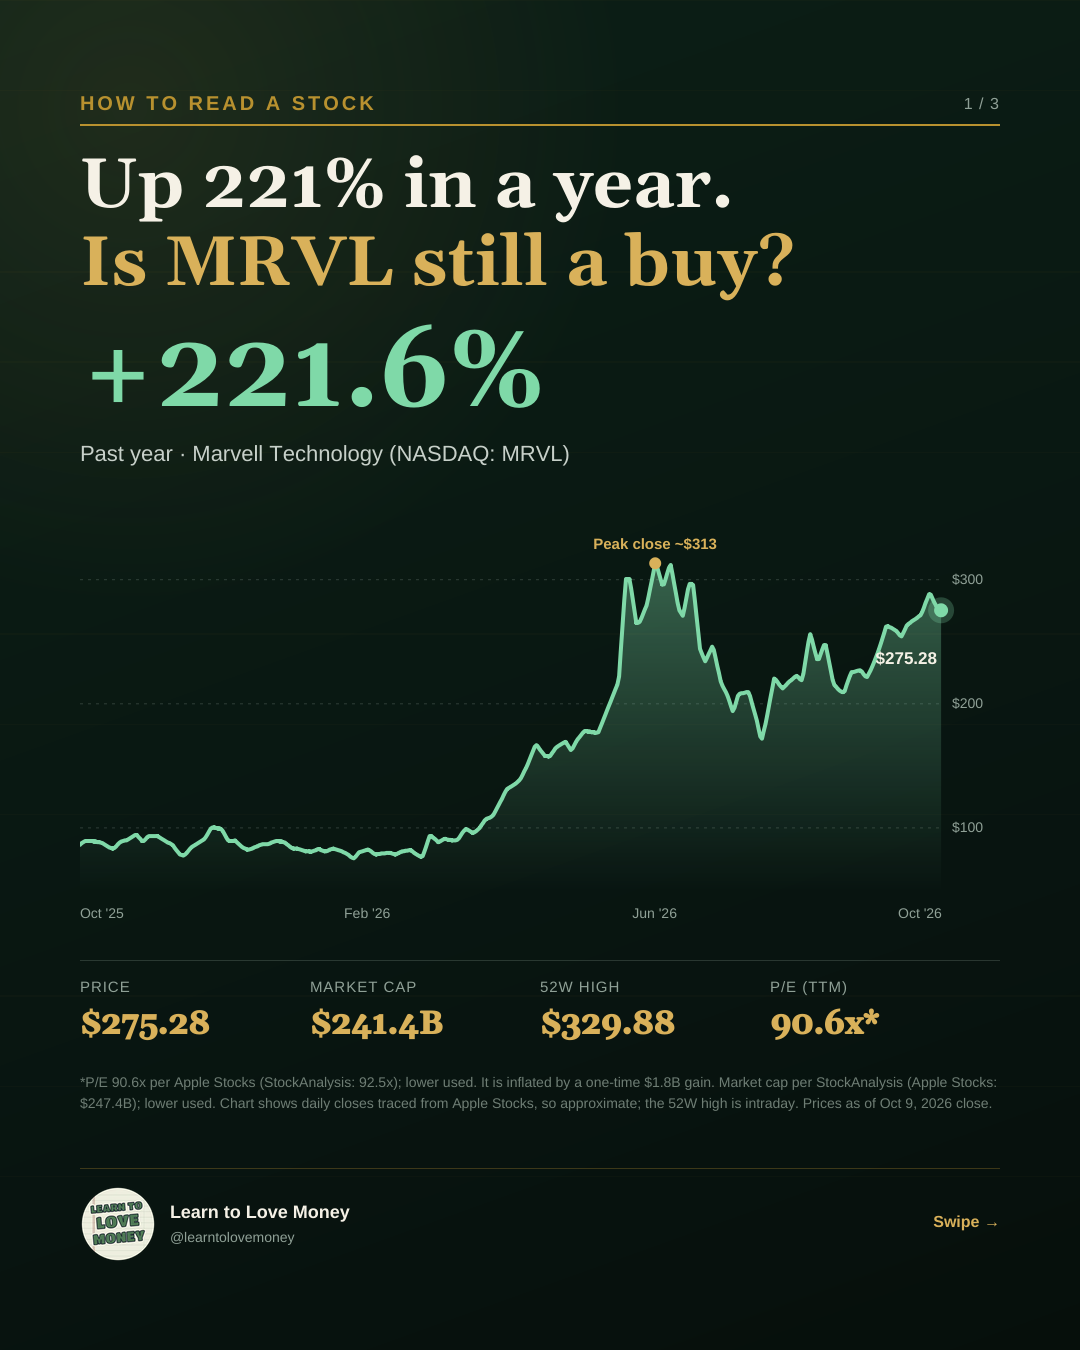
Marvell is up more than 220% in a year, data centers are now 79% of sales, and management just raised its FY2028 revenue target to about $20 billion. Analysts mostly rate it a Buy. Our AI would wait for a pullback. Here's why, and what would prove it wrong.
What Marvell actually does
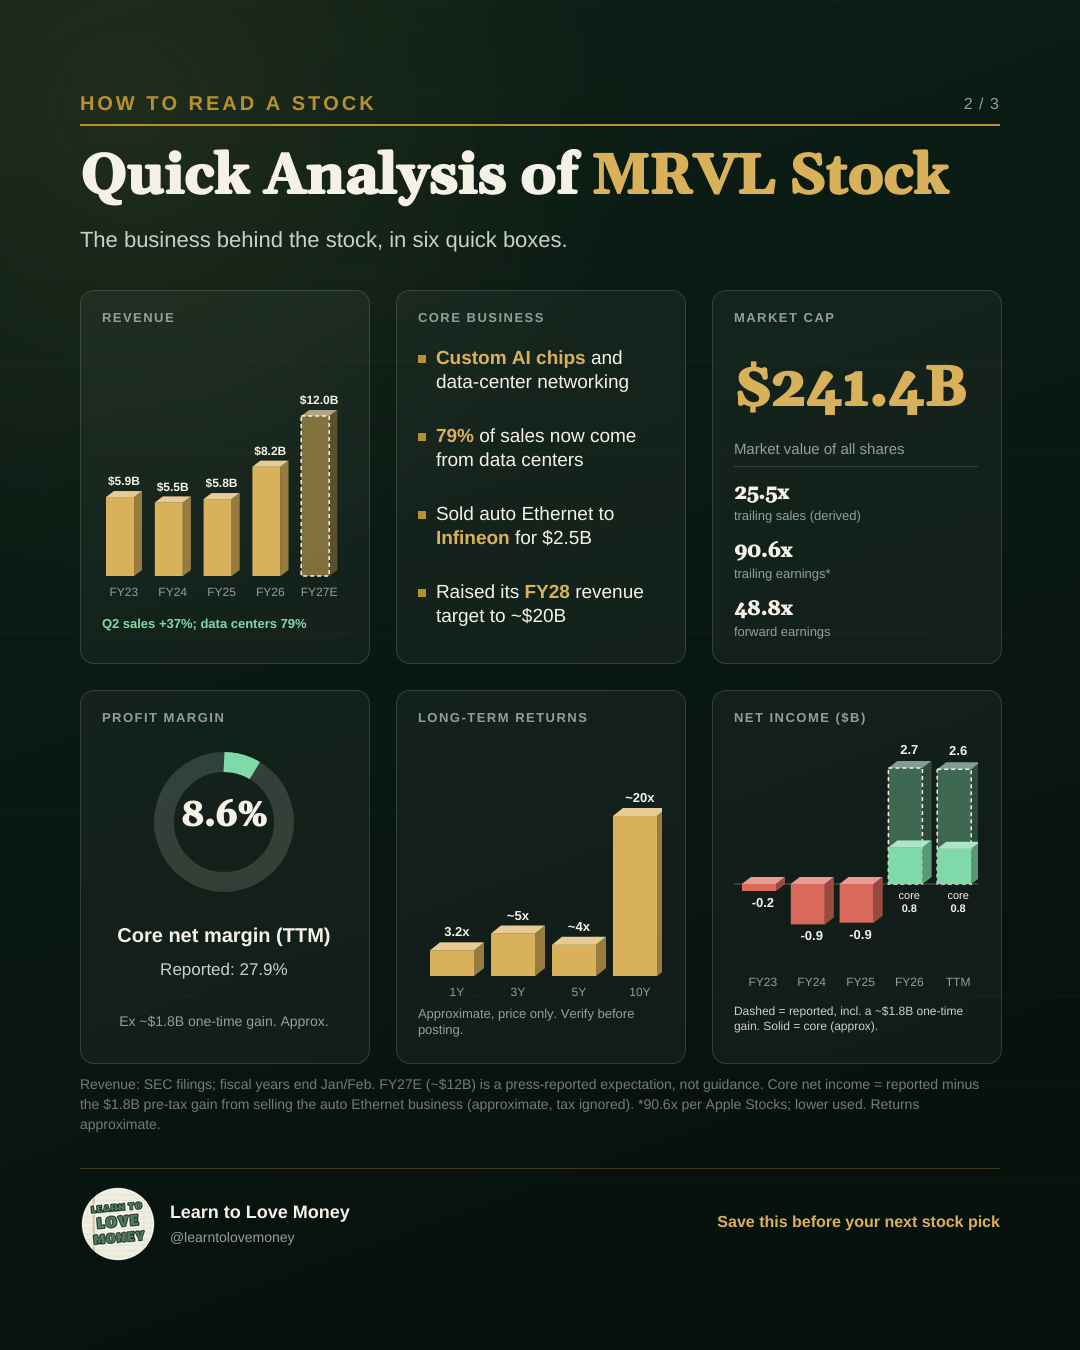
Marvell designs custom AI chips and the networking gear that moves data around data centers. Data centers are now 79% of sales. The company sold its auto Ethernet business to Infineon for $2.5 billion, and it raised its FY2028 revenue target to about $20 billion.
Growth: revenue and earnings
Revenue was flat for three years, at $5.9 billion in fiscal 2023, $5.5 billion in 2024, and $5.8 billion in 2025. Then it jumped to $8.2 billion in fiscal 2026, and the press-reported expectation for fiscal 2027 is about $12 billion. Second-quarter sales grew 37%. Fiscal years end in January or February.
Revenue ($B)
Reported earnings look much stronger than the real business. Reported net income was $2.7 billion in fiscal 2026, but that includes a one-time gain of about $1.8 billion from selling the auto Ethernet business. Without it, core net income was about $0.8 billion, a core net margin of 8.6% versus 27.9% as reported.
Net income ($B)
Is it actually cheap?
Price
$275.28
Market cap
$241.4B
52-week high
$329.88
P/E (TTM)
90.6x
The 90.6 P/E is inflated by that one-time gain, and even on the core figure it is not cheap. The stock trades at about 25.5 times trailing sales and 48.8 times forward earnings. Those are prices for years of flawless growth.
Long-term returns have been strong: roughly 3.2x over one year, about 5x over three, about 4x over five, and about 20x over ten (approximate, price only). After a run like that, there is little room for a stumble.
Moat and leadership
Morningstar gives Marvell a narrow moat, so it has some durable advantages in custom chips and networking. Leadership is strong: the company is executing, redeploying capital from the auto business, and guiding higher. Still, customers are a few giant AI buyers, and they can change plans.
The risk that flips the call
The risk to our SELL lean is that AI spending keeps accelerating and Marvell hits that $20 billion target early. If earnings grow into the valuation, today's price could look reasonable in hindsight. That is the bull case.
The AI verdict
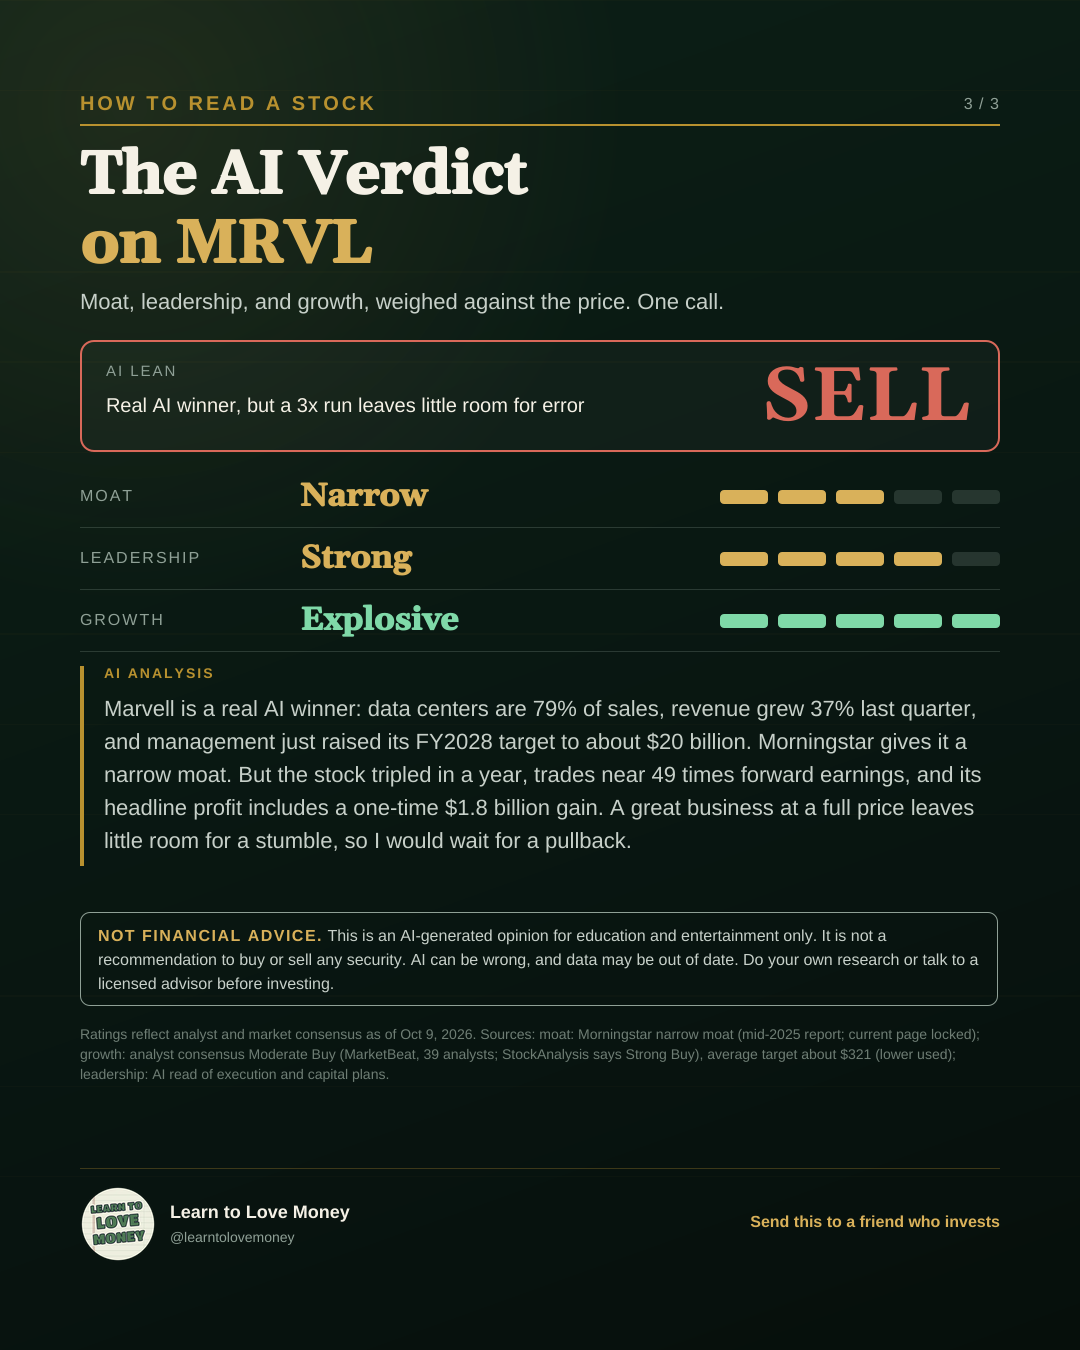
AI lean
Real AI winner, but a 3x run leaves little room for error
SELL
Weighing moat (narrow), leadership (strong), and growth (explosive) against the price, our AI leans Sell. Marvell is a great business, but the stock tripled in a year and trades near 49 times forward earnings. A great business at a full price leaves little room for a stumble, so we would wait for a pullback. Analysts are more bullish, so weigh both views.
More in this series: CoreWeave, Bloom Energy, TSMC, and Micron. And for the AI side, our free AI Explained course covers what AI is and where it can go wrong.
NOT FINANCIAL ADVICE. This is an AI-generated opinion for education and entertainment only. It is not a recommendation to buy or sell any security. AI can be wrong, and data may be out of date. Do your own research or talk to a licensed advisor before investing.
Sources
- SEC EDGAR: Marvell filings — fiscal results and the sale of the auto Ethernet business
- Apple Stocks app: one-year price history and market cap (no public link)
- StockAnalysis — market cap, P/E, and analyst ratings
- MarketBeat — analyst consensus (39 analysts)
- Morningstar — narrow moat rating