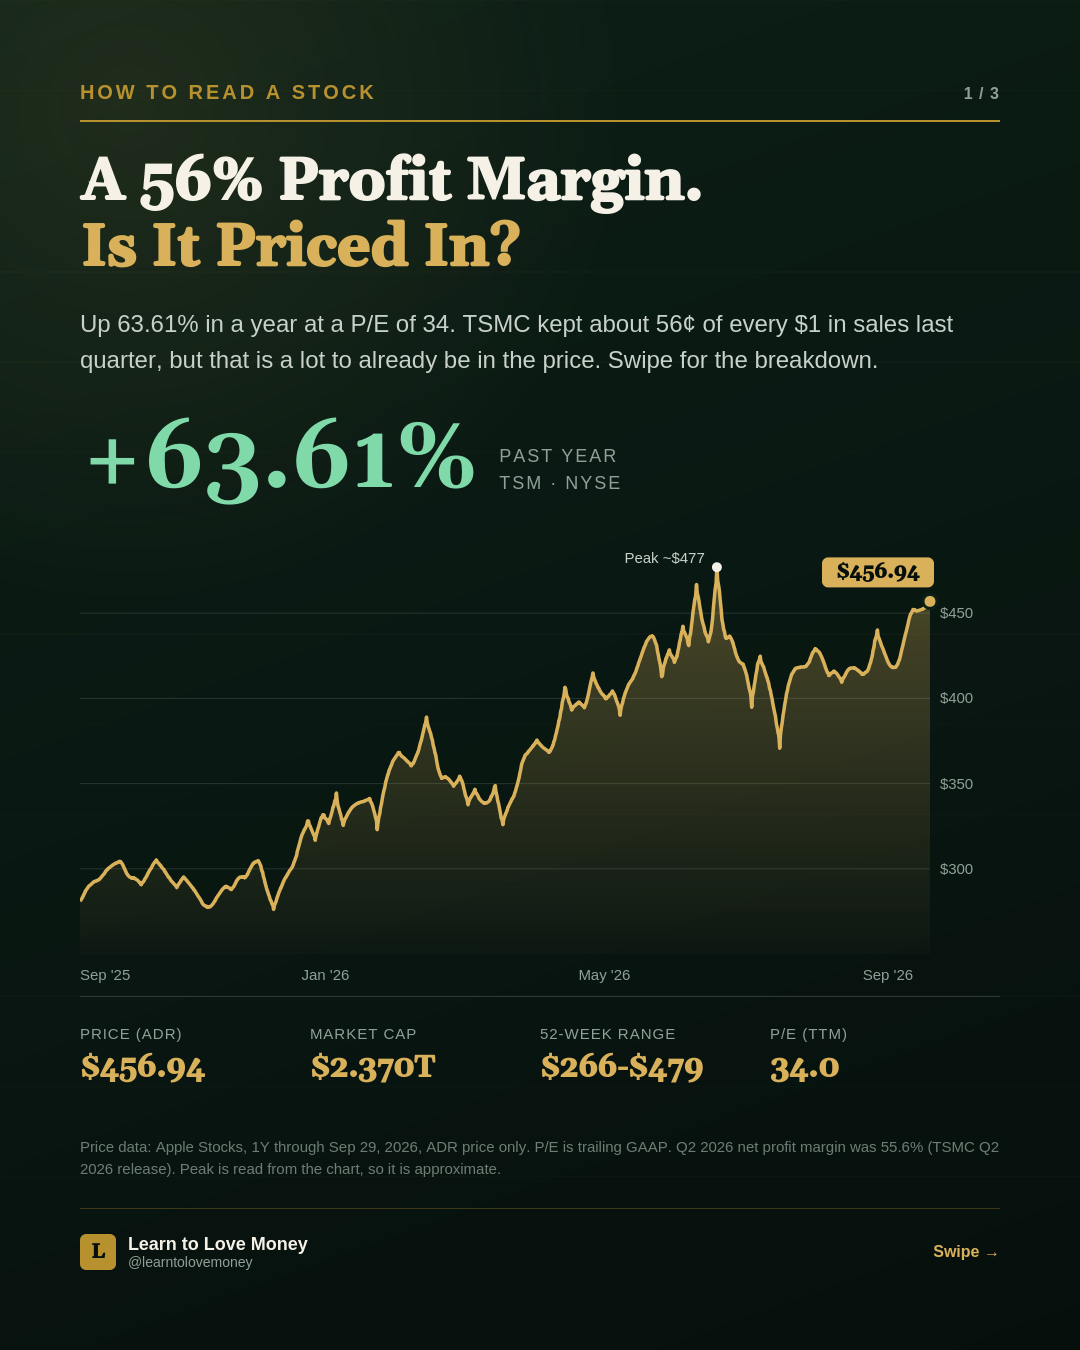
TSMC is up about 64% over the past year, kept about 56 cents of every dollar of sales as profit last quarter, and still trades at a P/E of 34. That's a lot of success to already be in the price. Here's what's underneath, and where our AI read lands.
What TSMC actually does
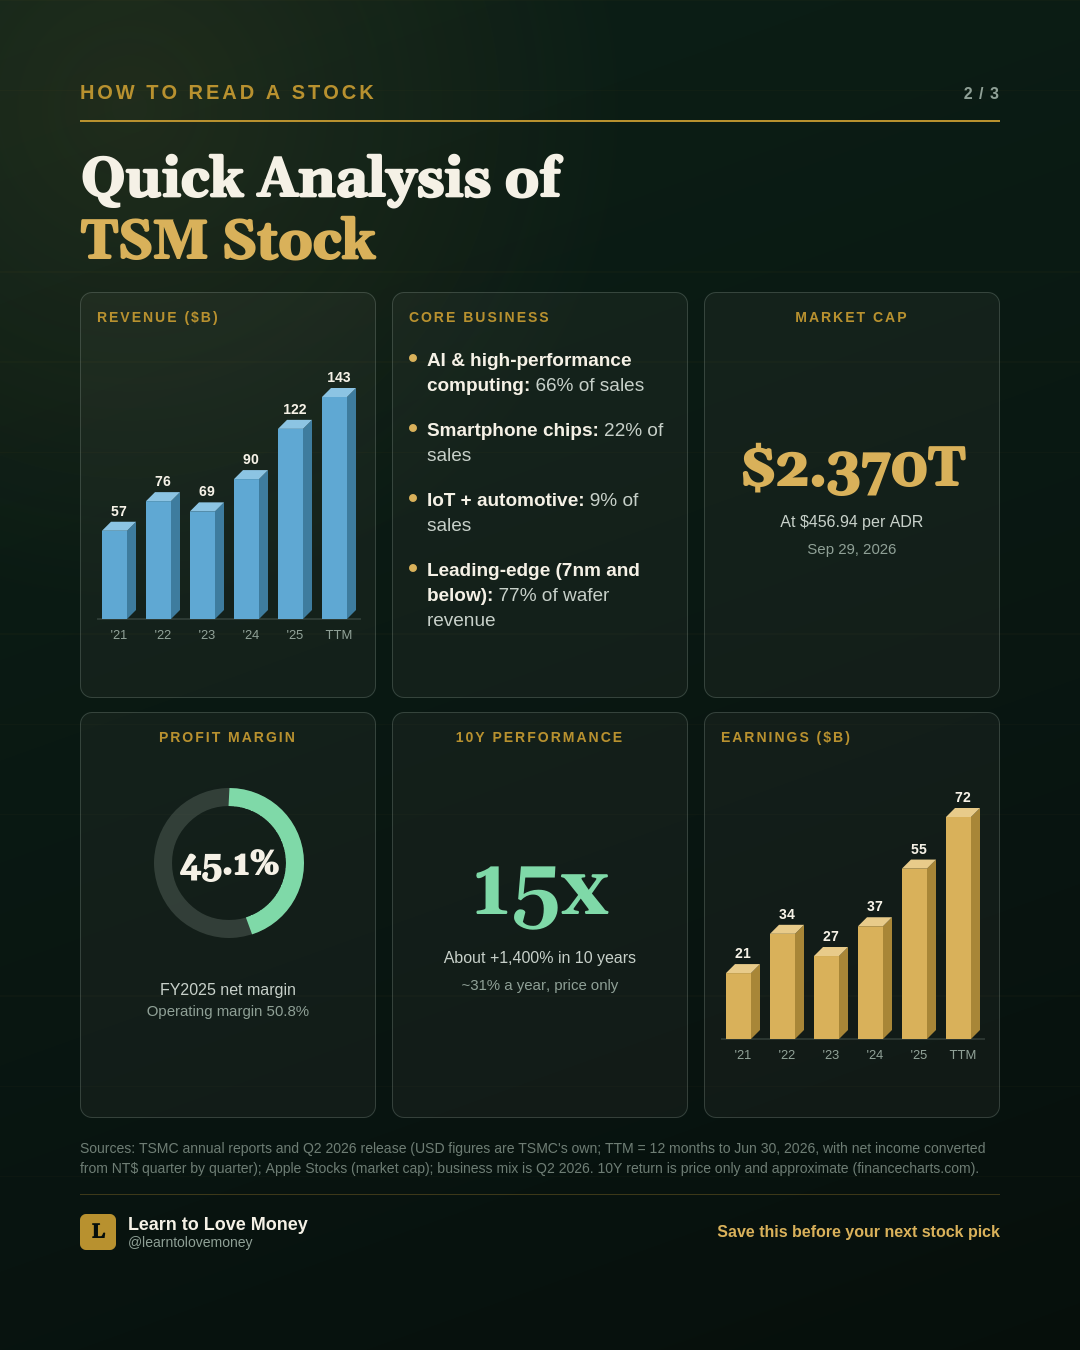
TSMC makes chips designed by other companies. It doesn't sell its own brand of processors; it manufactures them for the companies that do. AI and high-performance computing is now 66% of sales, smartphone chips are 22%, and IoT and automotive are 9%.
What sets it apart is the leading edge. Chips made on its most advanced processes, 7nm and below, are 77% of wafer revenue, and that's where the hardest-to-copy technology and the fattest margins sit.
Where sales come from
Growth: revenue and earnings
Revenue has climbed from $57B in 2021 to $122B in 2025, and $143B over the last twelve months (TTM). That works out to roughly 21% a year from 2021 to 2025, with one soft year in 2023 when it dipped from $76B to $69B.
Revenue ($B)
Earnings have grown even faster than sales. They reached $55B in 2025 and $72B over the last twelve months, helped by a FY2025 net margin of 45.1% and an operating margin of 50.8%. Last quarter alone, revenue grew 34% at a 55.6% net margin, and management now guides 2026 growth above 40%.
Earnings ($B)
Is it already priced in?
Price (ADR)
$456.94
Market cap
$2.370T
52-week range
$266–$479
P/E (TTM)
34.0
We didn't flag any large non-cash investment gains in TSMC's numbers, so the 34 P/E looks like a fair read of what you're paying for profit today. It's not cheap, and it already assumes that growth stays strong.
The case for the price rests on that growth. Morningstar puts fair value at $534, roughly 17% above today's price, and 20 of 21 analysts rate the stock Buy or Strong Buy. Over the last decade the stock has returned about 15x on price alone, roughly 31% a year.
Moat and leadership
Morningstar rates TSMC a wide moat. Building leading-edge chips takes enormous capital, years of accumulated know-how, and the trust of customers who can't afford to have their designs fail, and rivals have struggled to match it.
On leadership, CEO C.C. Wei has kept TSMC executing through the AI boom, with margins rising as demand surged. We rate leadership solid rather than exceptional because so much of the story still depends on one geography.
The risk that flips the call
TSMC still makes most of its chips in Taiwan, so geopolitical tension around the island is the risk that could flip this call. It's hard to predict and hard to hedge, and it's the reason a stock this good can still fall sharply on headlines alone. A slowdown in AI demand would hurt too, especially at a 34 P/E.
The AI verdict
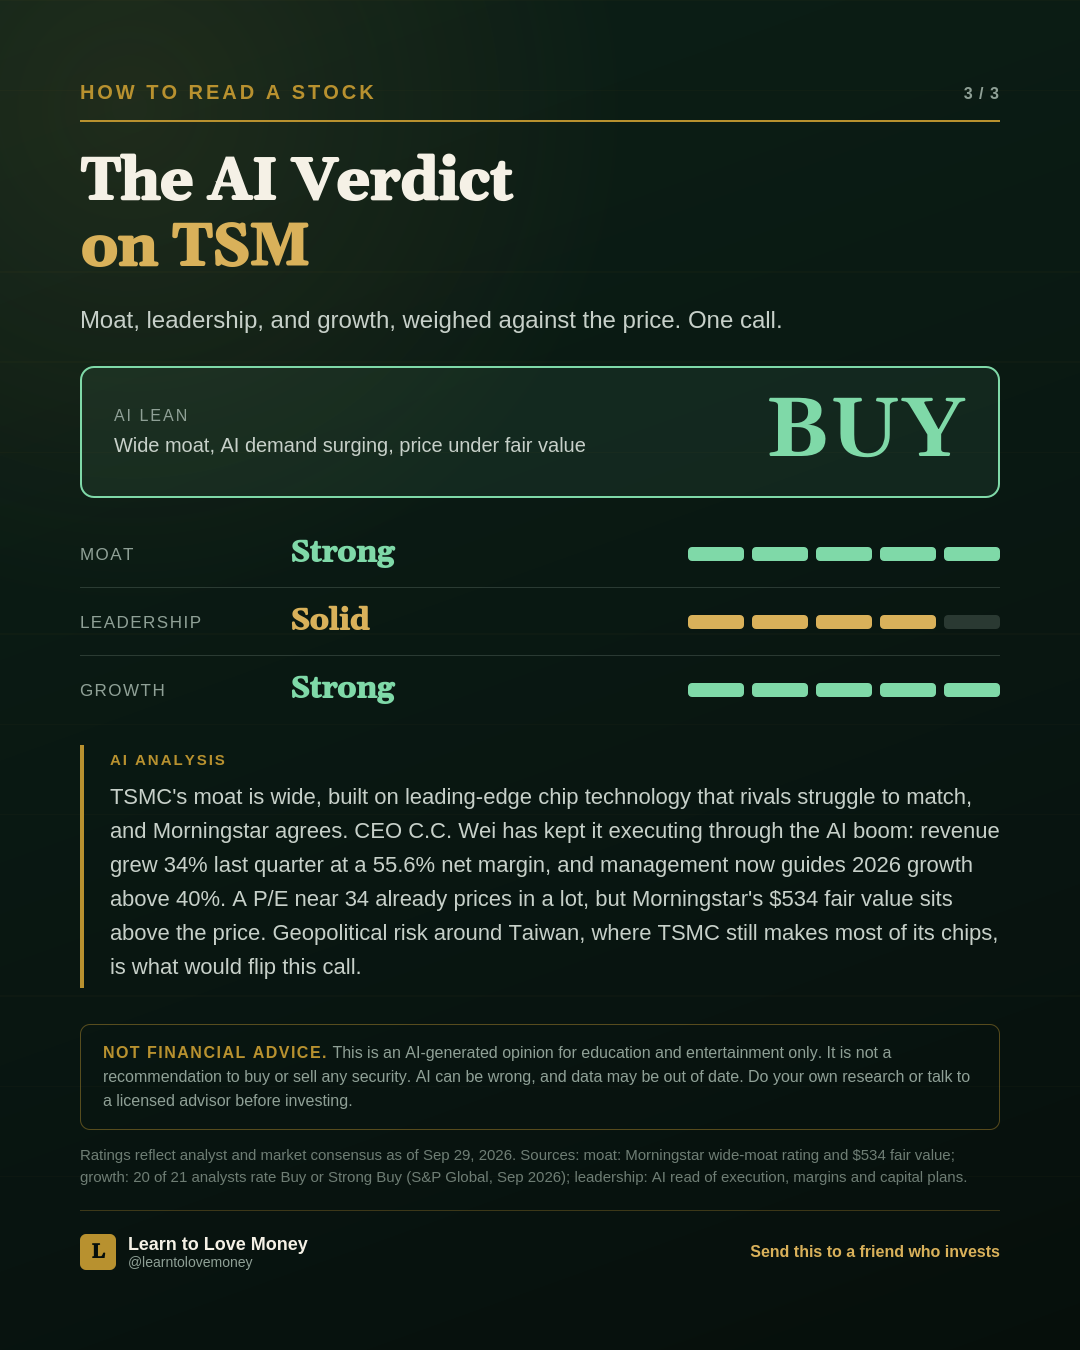
AI lean
Wide moat, AI demand surging, price under fair value
BUY
Weighing moat (strong), leadership (solid), and growth (strong) against the price, our AI leans Buy. The honest caveat is that at a 34 P/E, the stock has little room for growth to disappoint, and the Taiwan risk is real. Weigh both before leaning on the call.
More in this series: our Alphabet analysis and Amazon analysis. And for the AI side, our free AI Explained course covers what AI is and where it can go wrong.
NOT FINANCIAL ADVICE. This is an AI-generated opinion for education and entertainment only. It is not a recommendation to buy or sell any security. AI can be wrong, and data may be out of date. Do your own research or talk to a licensed advisor before investing.