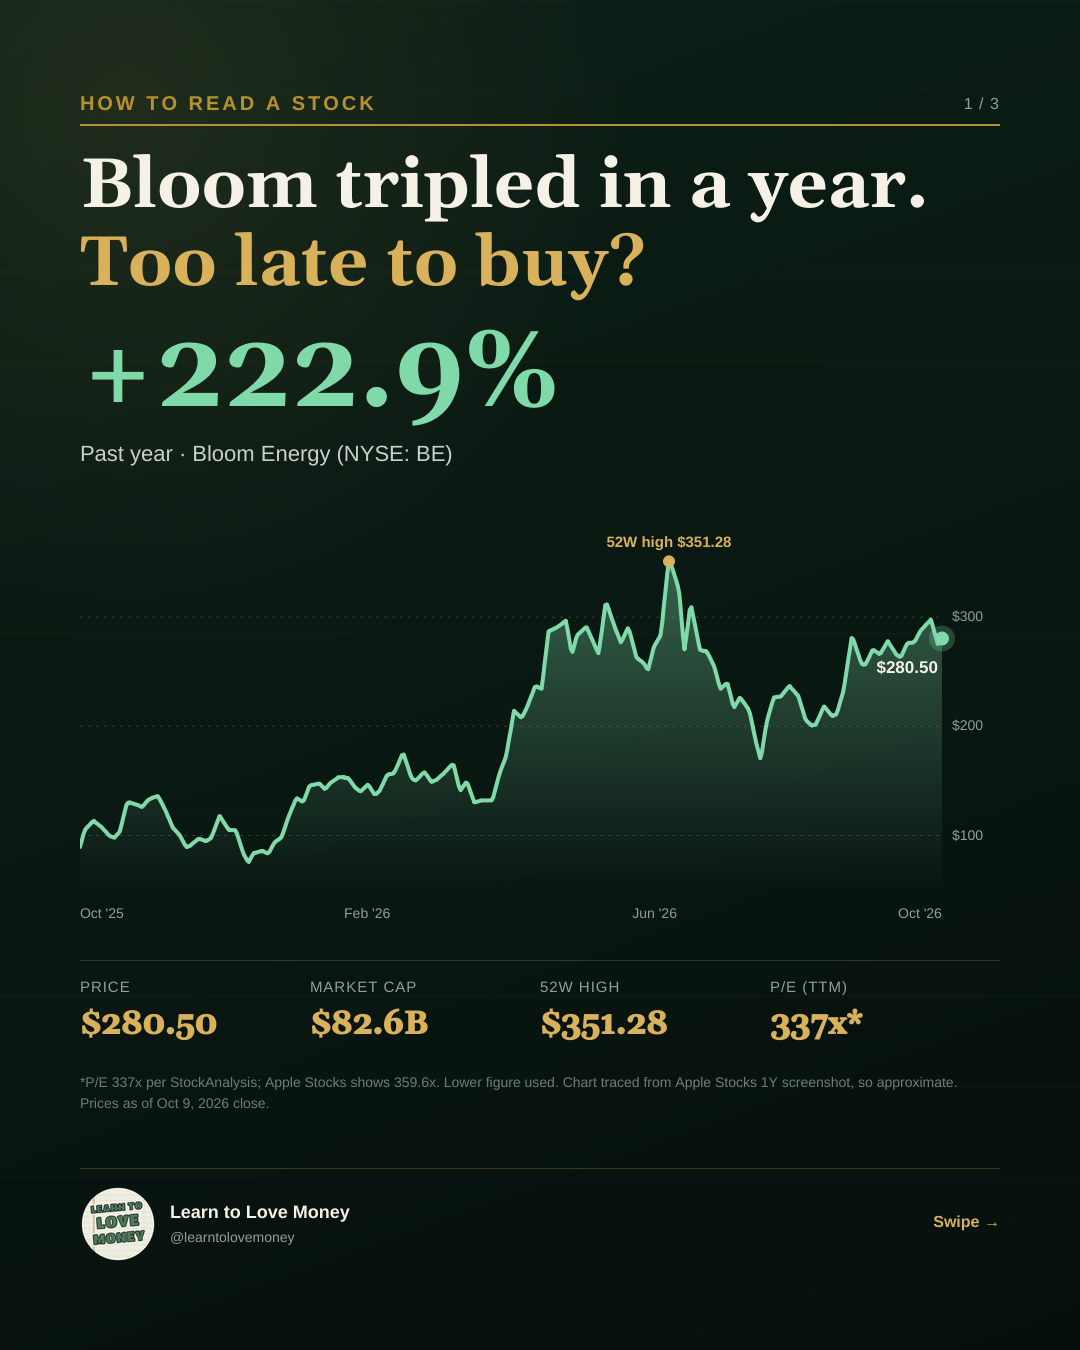
Bloom Energy has tripled in a year, revenue is guided to roughly double in 2026, and it just posted its first billion-dollar quarter. Analysts mostly rate it a Buy. Our AI would not chase it here. Here's why, and what would prove it wrong.
What Bloom Energy actually does
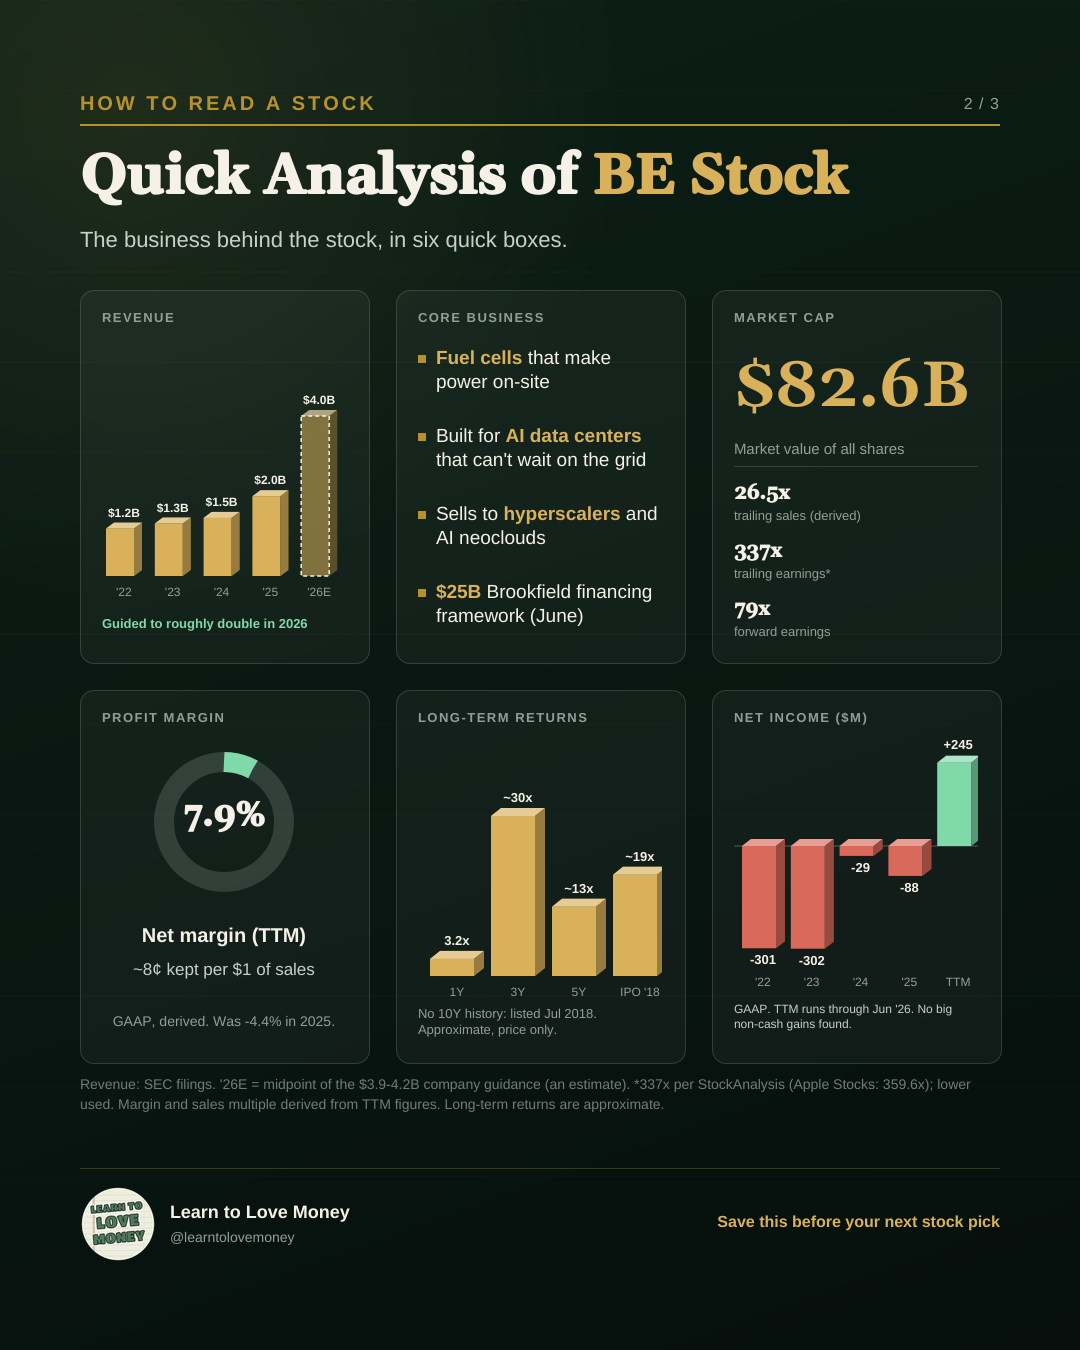
Bloom makes fuel cells that generate power on-site. They are built for AI data centers that cannot wait on the grid, and Bloom sells to hyperscalers and AI neoclouds. In June it announced a $25 billion financing framework with Brookfield.
Growth: revenue and earnings
Revenue grew from $1.2 billion in 2022 to $2.0 billion in 2025. Company guidance of $3.9 to $4.2 billion points to roughly $4.0 billion in 2026, about double.
Revenue ($B)
Bloom lost money every year from 2022 to 2025, then turned profitable over the trailing twelve months, with net income of $245 million. That is a net margin of about 7.9%, or roughly 8 cents kept per $1 of sales, versus -4.4% in 2025. A profit is a real milestone, but it is small next to the stock's price.
Net income ($M)
Is it actually cheap?
Price
$280.50
Market cap
$82.6B
52-week high
$351.28
P/E (TTM)
337x
No. The stock trades at about 26.5 times trailing sales, 337 times trailing earnings, and 79 times forward earnings. At those prices the market is paying for years of flawless execution.
Long-term returns are huge: about 3.2x in one year, about 30x in three, about 13x in five, and about 19x since the 2018 IPO (approximate, price only). A stock that has run this far can drop quickly on one soft quarter.
Moat and leadership
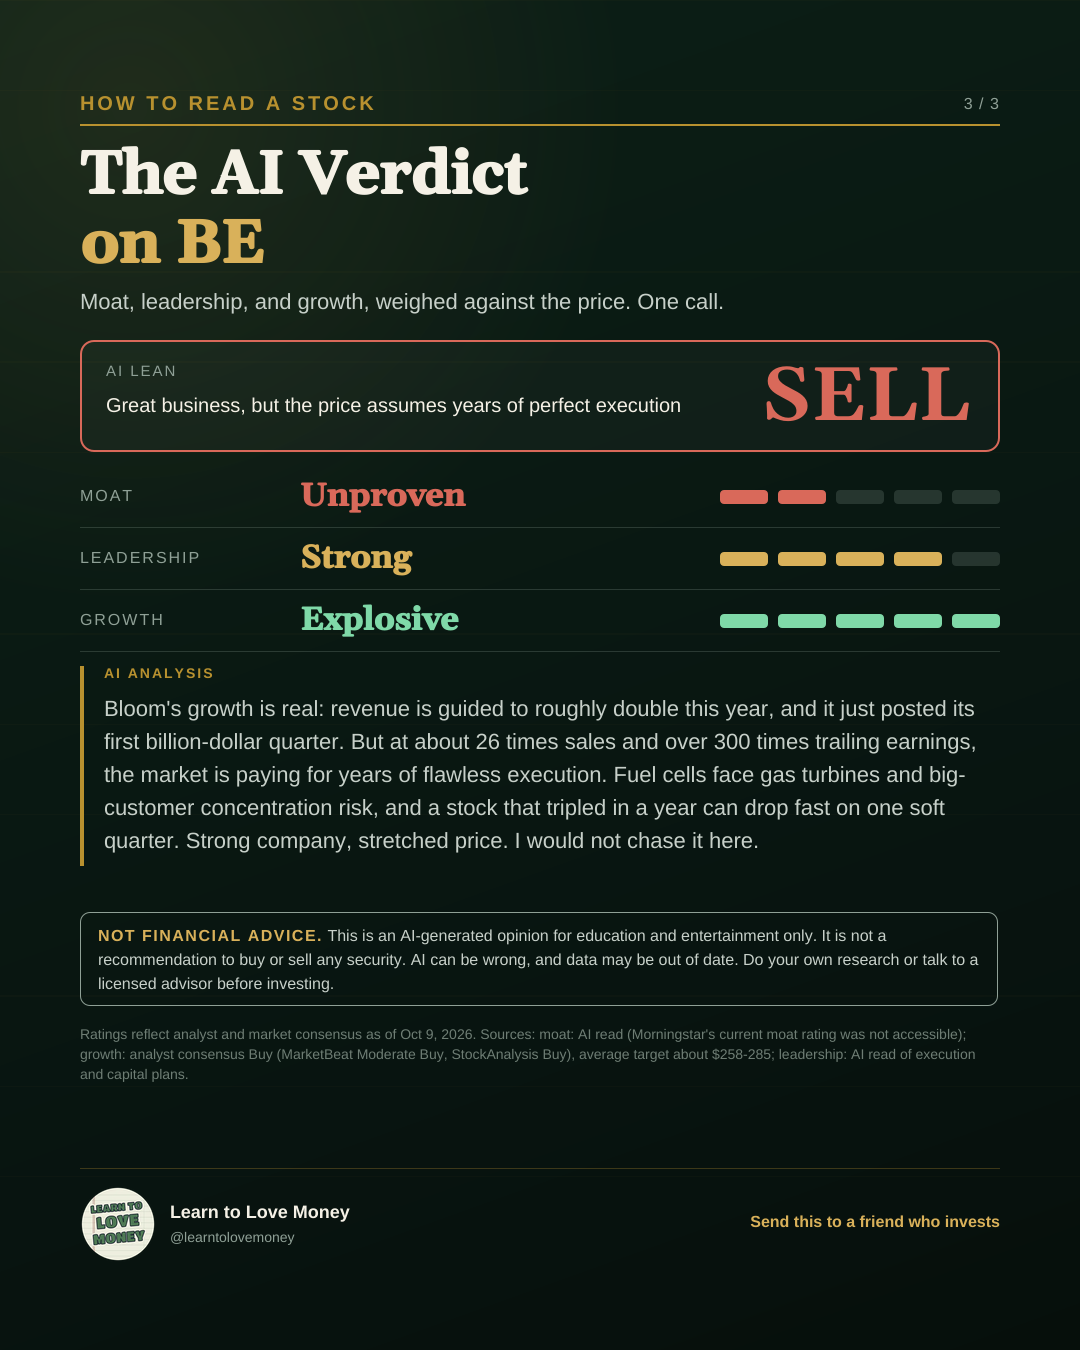
We rate the moat unproven. Morningstar's current moat rating was not accessible, so this is an AI read. Fuel cells face competition from gas turbines and other onsite power, and a few large customers make up much of demand. Leadership is strong: the company has executed on growth and secured big financing.
The risk that flips the call
The risk to our SELL lean is that the AI power shortage lasts longer than expected and Bloom keeps beating guidance. If sales and profits grow faster than the market assumes, the price could be justified. That is what the bulls are betting on.
The AI verdict
AI lean
Great business, but the price assumes years of perfect execution
SELL
Weighing moat (unproven), leadership (strong), and growth (explosive) against the price, our AI leans Sell. Bloom's growth is real, but at about 26 times sales and over 300 times trailing earnings, the stock leaves no room for a stumble. Strong company, stretched price: we would not chase it here. Analysts are more bullish, so weigh both views.
More in this series: CoreWeave, Marvell, Sandisk, and TSMC. And for the AI side, our free AI Explained course covers what AI is and where it can go wrong.
NOT FINANCIAL ADVICE. This is an AI-generated opinion for education and entertainment only. It is not a recommendation to buy or sell any security. AI can be wrong, and data may be out of date. Do your own research or talk to a licensed advisor before investing.
Sources
- SEC EDGAR: Bloom Energy filings — revenue, net income, and 2026 guidance
- Apple Stocks app: one-year price history and market cap (no public link)
- StockAnalysis — P/E, market cap, and analyst ratings
- MarketBeat — analyst consensus